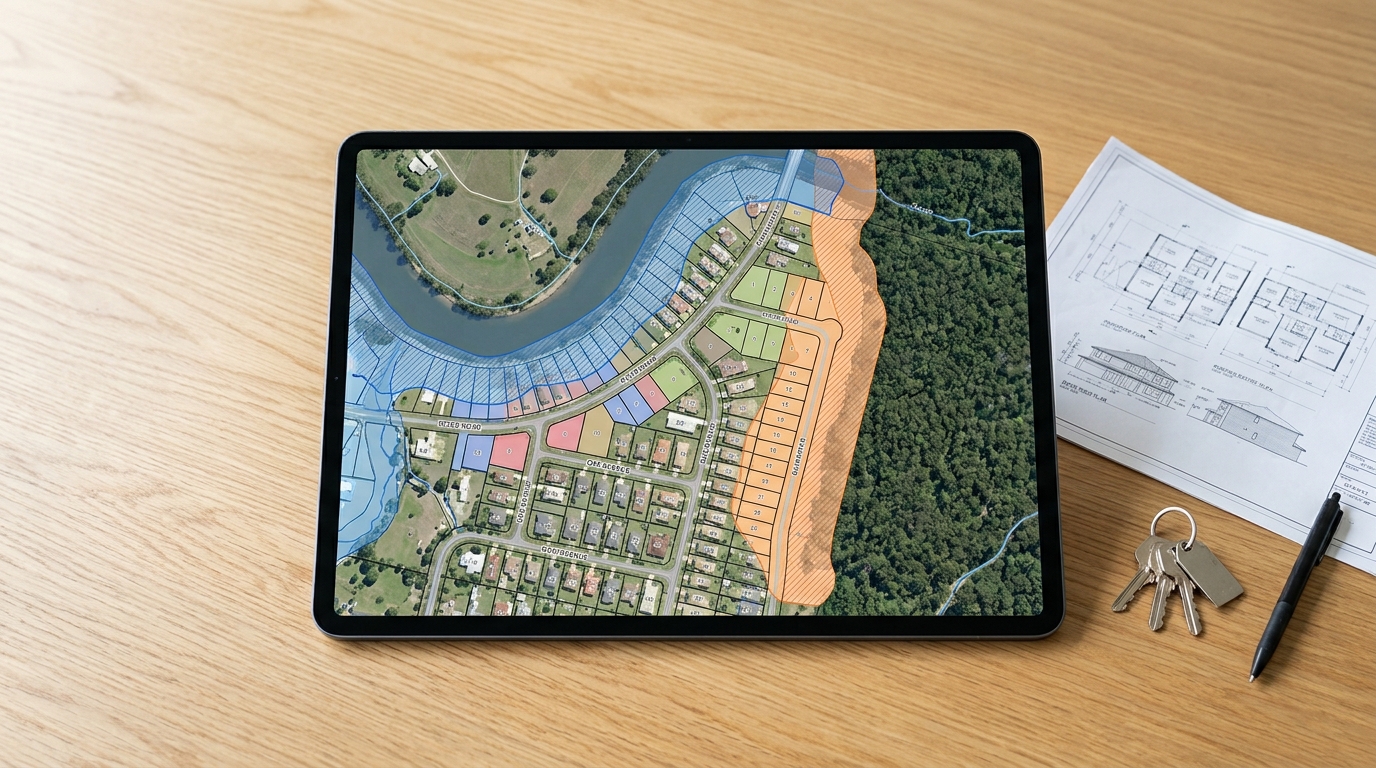
Before buying land or a house anywhere in Australia, it’s worth spending an hour to check flood and bushfire risk on the maps. Those overlays decide what you can build, what it costs to build it, whether you can insure it, and sometimes whether a bank will lend against it.
Most buyers check them too late, if at all. This guide walks through the main maps, how to read them, what the NSW planning certificate tells you, and the questions to ask before your contract goes unconditional.
This article was produced and reviewed by the Australia Develops editorial team. See our Editorial Policy for sourcing standards and methodology.
How Flood and Bushfire Risk Changes What a Property Costs You
Natural disaster risks directly dictate the ongoing holding costs and structural viability of Australian real estate investments.
When a property sits inside a high-risk area on the flood or bushfire maps, the financial impact goes well beyond the risk of physical damage.
Global reinsurance shifts and localized weather patterns have caused a sharp correction in how local underwriters calculate risk exposure.
For certain high-exposure allotments, annual property insurance premiums can escalate to exceptionally high figures, fundamentally altering the asset’s cash flow yield or making comprehensive coverage entirely unavailable.
Insurers use these maps alongside their own hydrological modelling, so their view of risk is often stricter than the council’s planning controls. A site the council is happy to approve for a house can still be one a major insurer won’t cover at a sensible price.
That is why getting a binding insurance quote during the cooling-off period, before contracts go unconditional, should be non-negotiable.
If one check had to be picked from this whole article, it would be the insurance quote. The maps and the planning certificate tell you what the rules are. The insurer’s price tells you what the risk will cost you every year you own the place, and it’s the number most buyers only discover after settlement.
| Financial and Regulatory Impact Vector | Risk Outcome if Checked Post-Purchase |
|---|---|
| Annual Insurance Premiums | Potential for extreme premium hikes or total refusal of flood/fire coverage. |
| Lending and Finance Approvals | Retail banks may lower the Loan-to-Value Ratio (LVR) or reject the mortgage entirely. |
| Structural Design Costs | Mandatory engineering upgrades, elevated floor levels, or fire-rated building materials. |
| Socio-Legal Restraints | Total restriction on footprint extensions, secondary dwellings, or future subdivisions. |
Why Growth Corridors Like Leppington Need These Maps Most
These environmental overlays matter most in the fast-growing greenfield corridors where new land releases are happening right now.
Leppington, part of Sydney’s South West Growth Area, is a prime example of a precinct where buyers must check the flood and bushfire maps before signing a contract, since new estates often sit close to overland flow paths and remnant bushland.
The video below breaks down the Leppington development pipeline and the planning considerations that shape land value there.
Map 1: Flood Planning Layers and How to Check Flood Risk
Comprehensive flood planning overlays identify historical inundation frequencies, overland flow paths, and structural stormwater constraints.
To accurately diagnose the hydrological risks of a parcel, buyers cannot rely solely on visual inspections or historical anecdotes.
Official hydrological mapping projects delineate land into specific zones based on the statistical probability of inundation occurrences, typically quantified as the Annual Exceedance Probability (AEP). The primary nationwide repository for historical and modeled hydrological data is the Australian Flood Risk Information Portal.
This platform aggregates state and local catchment studies to deliver data regarding regional flood behaviors.
When you look at a flood map, it helps to know the difference between these classifications:
- Flood Planning Area (FPA): Land below the 1% AEP flood level (commonly known as the 1-in-100-year flood level) plus a freeboard safety margin, usually an additional 0.5 metres of elevation.
- Overland Flow Path: The specific geographic corridor where excess rainwater flows across the surface of the ground during intense downpours when local subterranean drainage networks reach maximum capacity.
- Drainage Easements and Stormwater Constraints: Legally binding allocations on a property title that guarantee municipal access to underground infrastructure or surface channels, strictly preventing any permanent structural development over those sections.
Properties impacted by overland flow paths or formal drainage restrictions encounter rigorous development controls. If you plan to build or extend, councils will often ask for specialized hydrological civil engineering assessments.
These restrictions can severely diminish the building envelope, a risk explored thoroughly within the comprehensive Property Easements NSW guide.
Map 2: The Bushfire Prone Land Map
Official bushfire prone land maps determine the mandatory Bushfire Attack Level (BAL) ratings and construction standards for regional properties.
Wildfire risk management in Australia is governed by strict statutory frameworks that mandate specific defensive design mechanisms for properties situated near volatile vegetation. A site is formally designated as bushfire prone if it sits within, or in close proximity to, vegetation categories capable of sustaining a high-intensity fire path.
Buyers looking within New South Wales can execute an instant property assessment via the NSW Rural Fire Service bush fire prone land check portal to confirm if a specific lot falls inside a regulated zone.
Falling within a bushfire prone boundary triggers the application of Australian Standard AS 3959 (Construction of buildings in bushfire-prone areas). This standard details specific construction metrics across escalating Bushfire Attack Level (BAL) tiers.
Each BAL tier reflects the expected radiant heat exposure, measured in kilowatts per square metre:
Properties rated a BAL-40 or BAL-FZ rating face extraordinary building challenges. Structural compliance requires specialized non-combustible materials, toughened window glass configurations, automated exterior drenching systems, and specialized ember guards.
These requirements add significant capital strain to development budgets, as documented within the Hidden building costs in Australia framework.
Development approvals inside these zones mandate the creation of a permanent Asset Protection Zone (APZ). The APZ acts as a cleared buffer area between the home and the surrounding bushland.
That buffer can significantly limit where a house can sit on the block. Councils also require clear vehicle evacuation routes so occupants can get out safely in an emergency.
NSW Section 10.7 Planning Certificates
The Section 10.7 Planning Certificate serves as the definitive legal disclosure document for environmental constraints on NSW land.
In New South Wales, the spatial data visible on open-source public mapping systems is legally anchored within the Section 10.7 Planning Certificate (previously known as the Section 149 Certificate).
This statutory document is issued by the local municipal council and must be attached to the vendor’s contract of sale by law.
Relying purely on a visual check of public web maps without examining this certificate introduces significant legal exposure.
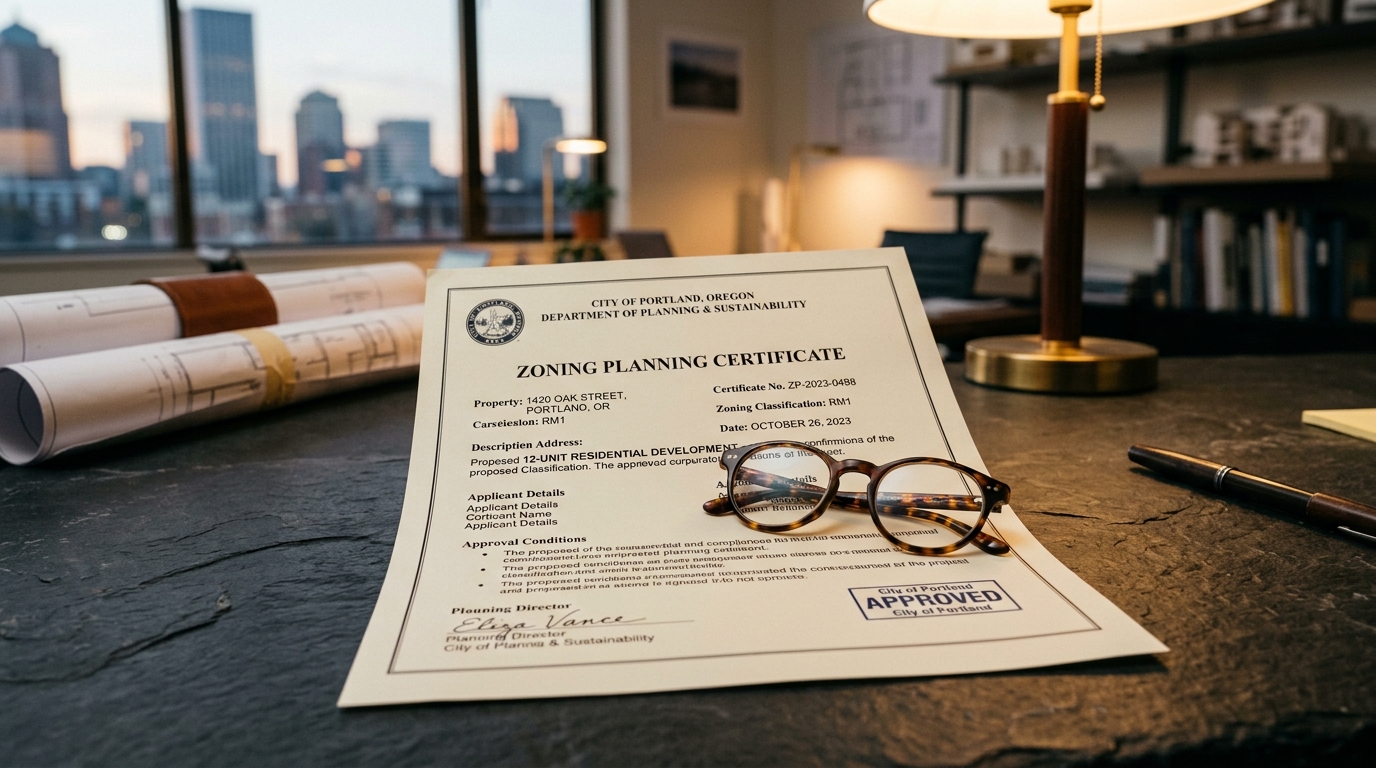
The document is typically split into two distinct tiers of information disclosure:
Section 10.7(2) certificate: sets out the core planning facts for the lot, including its zoning, whether complying development applies, and whether the land is identified as bushfire prone or flood affected.
Section 10.7(5) certificate: adds wider context the council holds about the land.
This document includes supplementary details regarding historical land use patterns, known regional climate vulnerabilities, council policy drafts, and specific subterranean stability factors such as loose-fill asbestos or acid sulfate soils.
If you’re planning to add a granny flat or another secondary dwelling, a single restrictive notation on the Section 10.7 certificate can stop the plan entirely.
For a closer look at the compliance pathways and development limits governed by these certificates, refer to the Granny flat NSW approval and costs breakdown.
Mapping Tools by State
Australian states maintain independent spatial information systems to manage localized flood and bushfire hazard tracking.
Land administration is run by each state, so the mapping tools, terminology and portals differ depending on where the property is.
Buyers managing a portfolio across state lines must adapt to distinct digital spatial mapping environments to perform consistent environmental due diligence.
The primary planning platform in New South Wales is the NSW Planning Portal Spatial Viewer, which brings together comprehensive local environmental plan (LEP) data, heritage protections, and hazard maps into a single interactive portal.
Other eastern states manage these environmental layers through dedicated regional portals.
| Jurisdiction | Primary Hazard Mapping Platform | Key Native Interface Strengths |
|---|---|---|
| New South Wales (NSW) | NSW Planning Portal Spatial Viewer | Streamlined lookup of LEP layers, bushfire perimeters, and zoning boundaries. |
| Queensland (QLD) | FloodCheck Queensland | Extensive historical flood monitoring data and river catchment models. |
| Victoria (VIC) | Victoria VicPlan | Instantaneous generation of official property planning zoning reports. |
Take extra care with land that isn’t registered yet or is part of an upcoming master-planned release, because the state portals may not show the final lot layout.
For a breakdown of the structural delays and environmental validation risks associated with new land releases, consult the Unregistered land Australia guide.
Red Flags to Watch for on the Maps
Specific visual patterns and spatial markers on official mapping tools signal severe underlying land development risks.
Interpreting digital hazard maps requires looking beyond whether a specific land lot is colored red or blue. Savvy property buyers scrutinize surrounding topographies and broader catchment layouts to spot hidden operational vulnerabilities.
Identifying these spatial anomalies early protects buyers from purchasing land that could become isolated or impossible to build on in the future.
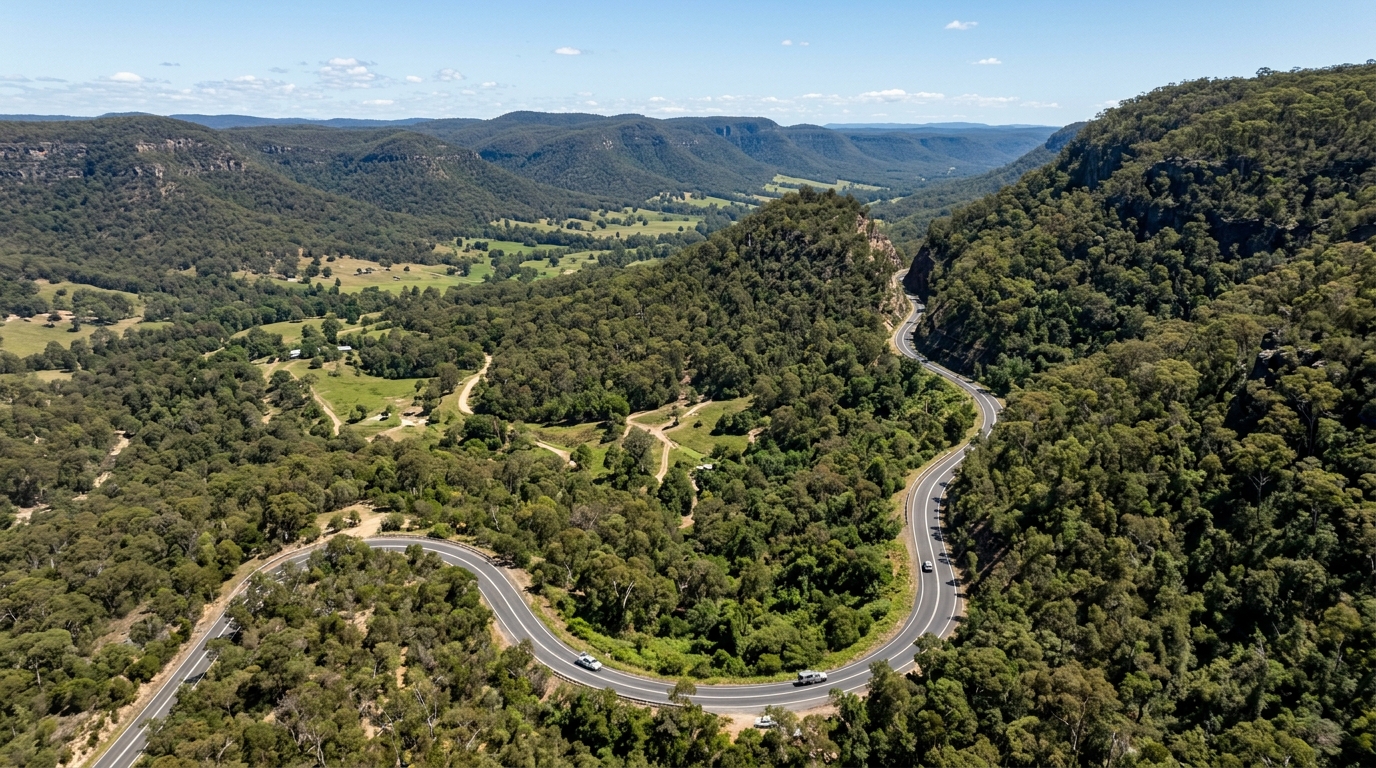
The island effect: a property can sit entirely outside a high-risk flood or bushfire zone while its only access road runs straight through one.
During a natural disaster, this creates a dangerous isolation trap, cutting off emergency evacuation routes and emergency services.
| Visual Map Phenomenon | Technical Subtext | Immediate Practical Risk for Buyers |
|---|---|---|
| Hazard Fringe Boundaries | The lot sits within 100 metres of a primary Category 1 vegetation perimeter. | Mandatory BAL assessment required; buffer zones may encroach on building plans. |
| Island Isolation Topography | The lot is high, but all surrounding access roads sit in low-lying, flood-prone valleys. | Complete loss of physical access during weather crises; high insurance risk. |
| Unmapped Local Creeks | Minor watercourses running through rural land without formal flood modeling layers. | Council may demand a custom, expensive hydrological study before approving a build. |
| Catchment Funnels | The property sits at the lowest point of an extensive suburban street system. | High vulnerability to local flash flooding and severe overland stormwater runoff. |
Evaluating these spatial patterns is especially critical for complex multi-dwelling projects or site subdivisions. The structural layout of access routes and asset placement can determine whether a project succeeds or fails, as outlined in the Dual occupancy Australia guide.
Questions to Ask Before You Sign
Direct, targeted questions to core professionals will uncover hidden environmental liabilities before a contract becomes binding.
The maps are only a starting point. Use questions like these to check what you’ve found with the people involved in the purchase:
Questions for a Solicitor or Conveyancer
“Does the attached Section 10.7(2) certificate disclose any historical council resolutions regarding flood mitigation or land slip policies affecting this specific lot?”
“Are there any unregistered drainage or access easements listed within the property’s primary title documents that do not appear on the public web maps?”
Questions for Local Council Planning Officers
“What is the exact minimum habitable floor level elevation mandated for new residential builds or major extensions on this site?”
“Are there active draft amendments to the Local Environmental Plan that will alter the current bushfire prone land classifications for this street?”
Questions for Insurance Underwriters
“Does your company classify this specific lot address under a high-risk hydrological category, and what is the exact quote for comprehensive flood and storm cover?”
“Will the presence of nearby Category 2 bushfire vegetation prevent me from securing a standard residential landlord protection policy?”
Questions for a Builder or Project Architect
“Based on the mapped bushfire data, what BAL rating is being factored into the preliminary construction budget, and how will that affect material choices?”
“Will the mapped overland flow path require pier-and-beam foundations rather than a standard, cost-effective concrete slab?”
Final Pre-Contract Checklist
Complete these steps systematically before executing an unconditional contract of sale on any Australian land parcel.
- Verify Property Address on State Portals: Enter the exact Lot and Deposited Plan (DP) number into the NSW Planning Portal Spatial Viewer or the relevant state’s equivalent platform to confirm active constraint layers.
- Review the Statutory Planning Certificate: Confirm that the Section 10.7 certificate matches the online map data and check for any restrictive notations.
- Run a Bushfire Boundary Check: Use the NSW Rural Fire Service bush fire prone land check portal to measure the exact distance between the planned building envelope and the nearest regulated vegetation boundaries.
- Cross-Reference Regional Flood Registries: Search the Australian Flood Risk Information Portal to check for any historical catchment studies or local flood data recorded for the neighborhood.
- Secure Written Insurance Quotes: Obtain a binding, formal property insurance quote that explicitly includes flood and bushfire cover, ensuring the ongoing holding costs remain viable.
- Confirm Safe Evacuation Access: Check the local road topography to ensure the property maintains clear, dependable emergency access routes that sit above maximum modeled flood levels.
This article is general information only and is not financial, legal or planning advice. See the Disclaimer for details.
Related Reading
- Unregistered Land Australia: Why Off-the-Plan Land Can Go Badly Wrong
- Property Easements NSW 2026: Types, Buyer Risks, Costs and Legal Solutions
- Worst Builders Australia: How to Check Builder Licence, Suspension and Disciplinary Records
- Austral Precinct Development 2026: Land, Lots and Long-Term Potential
- Sloping Block Site Costs Australia: Why Cheap Land Can Cost More to Build On