The 5% Deposit Scheme, officially the First Home Guarantee, is not the scheme people were weighing up a year ago. Since October 2025 there is no income cap, no annual limit on places and a higher price cap everywhere, and uptake has jumped to match.
That has made it the default way in for a lot of first home buyers, and it has started to show up in entry-level prices too. Below is how the scheme works now, what the caps let you buy, and the side effect buyers should weigh up before using it.
How the Scheme Works Right Now
The mechanics haven’t changed: you buy with as little as a 5% deposit, and the Government guarantees the bank up to 15% of the property’s value so you skip Lenders Mortgage Insurance entirely, an upfront saving that typically runs $15,000 to $35,000 on a metro purchase. What changed is who can get one. Housing Australia’s First Home Guarantee page confirms the scheme now has no income test and no cap on the number of guarantees issued in a year, both removed from 1 October 2025. Previously the scheme capped out at 35,000 places a year and excluded anyone earning over $125,000 solo or $200,000 as a couple; both of those limits are gone.
You still need to be a first home buyer or have had no property interest in the past ten years, intend to live in the property, and be an Australian citizen or permanent resident. You also still need to service the loan on a 5% deposit, which is a bigger loan and a bigger repayment than a 20% deposit buyer carries on the same property.
First Home Guarantee Price Caps: What You Can Buy
Every price cap rose in October 2025, and in most growth corridors this site covers, the cap now sits well above what you’d pay. The full national table, from Housing Australia’s property price cap tool, looks like this:
| Location | Price Cap |
|---|---|
| NSW — Sydney, Illawarra, Newcastle, Lake Macquarie | $1,500,000 |
| NSW — other regions | $800,000 |
| VIC — Melbourne, Geelong | $950,000 |
| VIC — other regions | $650,000 |
| QLD — Brisbane, Gold Coast, Sunshine Coast | $1,000,000 |
| QLD — other regions | $700,000 |
| WA — Perth | $850,000 |
| WA — other regions | $600,000 |
| SA — Adelaide | $900,000 |
| SA — other regions | $500,000 |
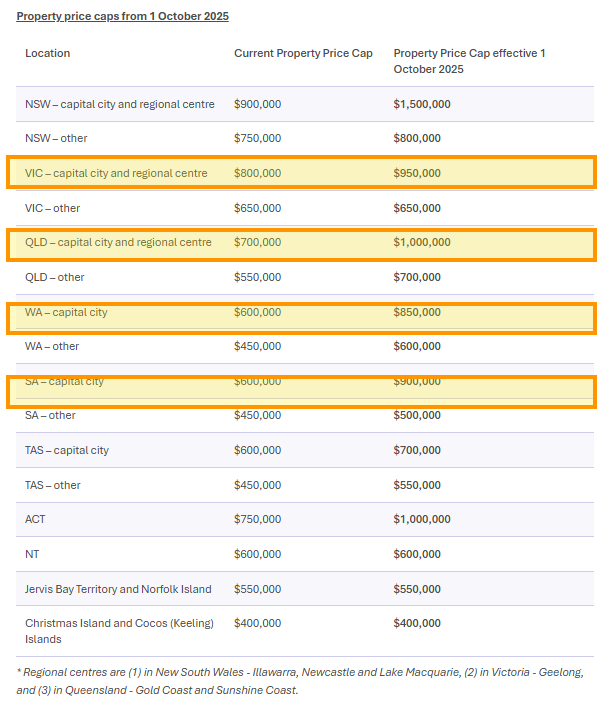
Set against the growth corridors this site tracks, that headroom is significant. Yarrabilba and Ripley Valley sit well under Brisbane’s $1,000,000 cap, Wyndham Vale sits under Melbourne’s $950,000, Alkimos sits under Perth’s $850,000, and Angle Vale sits under Adelaide’s $900,000. A new-build purchase in any of these corridors is realistically a 5% deposit purchase under this scheme, not a marginal case up against the ceiling.
Why Removing the Income Cap Changed Who Hits the Price Cap
Take away the income test and the annual cap, and the uptake numbers move fast. Housing Australia issued 22,921 guarantees in the four months after the October changes, against 13,105 in the four months before, a 75% jump. Roughly two-fifths of that group are under 30, more than 10,700 buyers are in regional areas, about 18% are key workers, and nearly two-thirds bought a house rather than a townhouse or apartment. This isn’t a scheme sitting unused waiting for eligible applicants anymore; it’s now the default entry point for a large share of first home buyers.
The Side Effect Nobody Fully Priced In
More buyers chasing the same entry-level stock has a predictable effect on entry-level prices. Cotality research found homes priced under the relevant cap rose 6.7% in the six months after the expansion, against 3.6% for higher-priced properties in the same markets, nearly double the growth rate. Sydney showed the widest gap: homes under the cap rose 4.1% while pricier properties fell 1.1%. Cotality’s research director Tim Lawless put it plainly: the scheme “works against the goal of improving housing affordability by boosting demand without addressing supply.”
That’s the trade-off worth understanding before you use it. The 5% deposit and skipped LMI are a genuine saving on the way in, but if you’re buying in a price bracket the scheme has made more competitive, some of that saving is being absorbed by faster price growth on the exact stock you’re competing for.
The scheme is worth using if buying at that price was the plan anyway. Stretching up towards the cap just because the scheme makes it possible is best avoided. That is the part of the market where prices have run hardest since the change, and a 5% deposit leaves very little equity buffer if it cools.
What This Means If You’re Buying Under the Price Cap
If you’re buying in a growth corridor comfortably under the local cap, the scheme is straightforwardly useful: it gets you in years earlier than saving a 20% deposit would, and the LMI saving alone is worth $15,000 to $35,000 depending on the loan size. The catch is competition, not eligibility. With income and place caps gone, more buyers at your price point are chasing the same new-release stock, so the advantage is real but it isn’t uncontested. Getting pre-approved and moving decisively on a release once you’ve done your research matters more than it used to.
If you’re closer to the price cap in your region, run the numbers on a 5% deposit loan specifically. A bigger loan means bigger repayments, and the interest rate environment right now (see the separate look at where interest rates are headed through 2027) makes that repayment stress test worth taking seriously before you commit.
The scheme changes how much deposit you need, not whether now is the right time to buy. For that side of the decision, see the NSW property market: buy now or wait analysis.
General information only, not personal financial advice. Based on Housing Australia and property data published as at September 2026. Scheme rules and price caps change, so confirm current details with a participating lender or Housing Australia.