The negative gearing changes in the 2026 budget rewrote the tax rules for property investors. From 1 July 2027, negative gearing depends on whether the property is new or established, and capital gains tax is being reworked from the same date. If you already own an investment property, very little changes for it. If you’re buying another one, almost everything does.
Here is how the rules apply by date, and what to focus on if you’re weighing up a purchase.
Negative Gearing Changes 2026: What the Rules Look Like Now
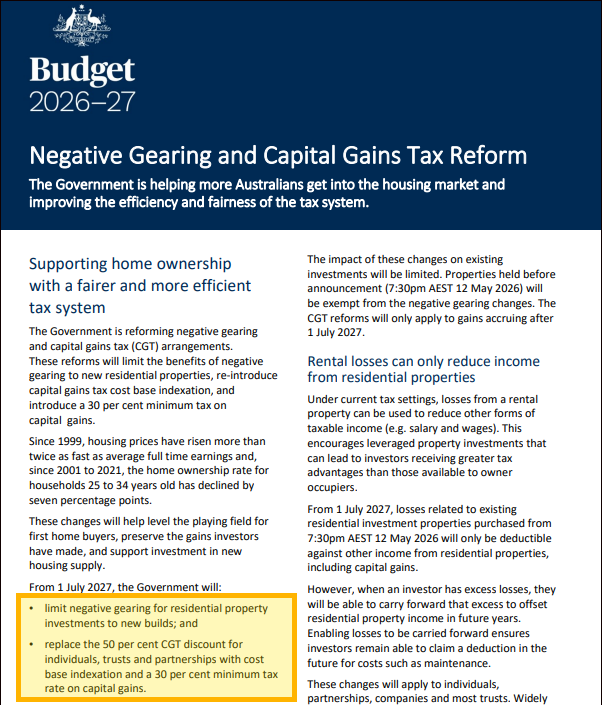
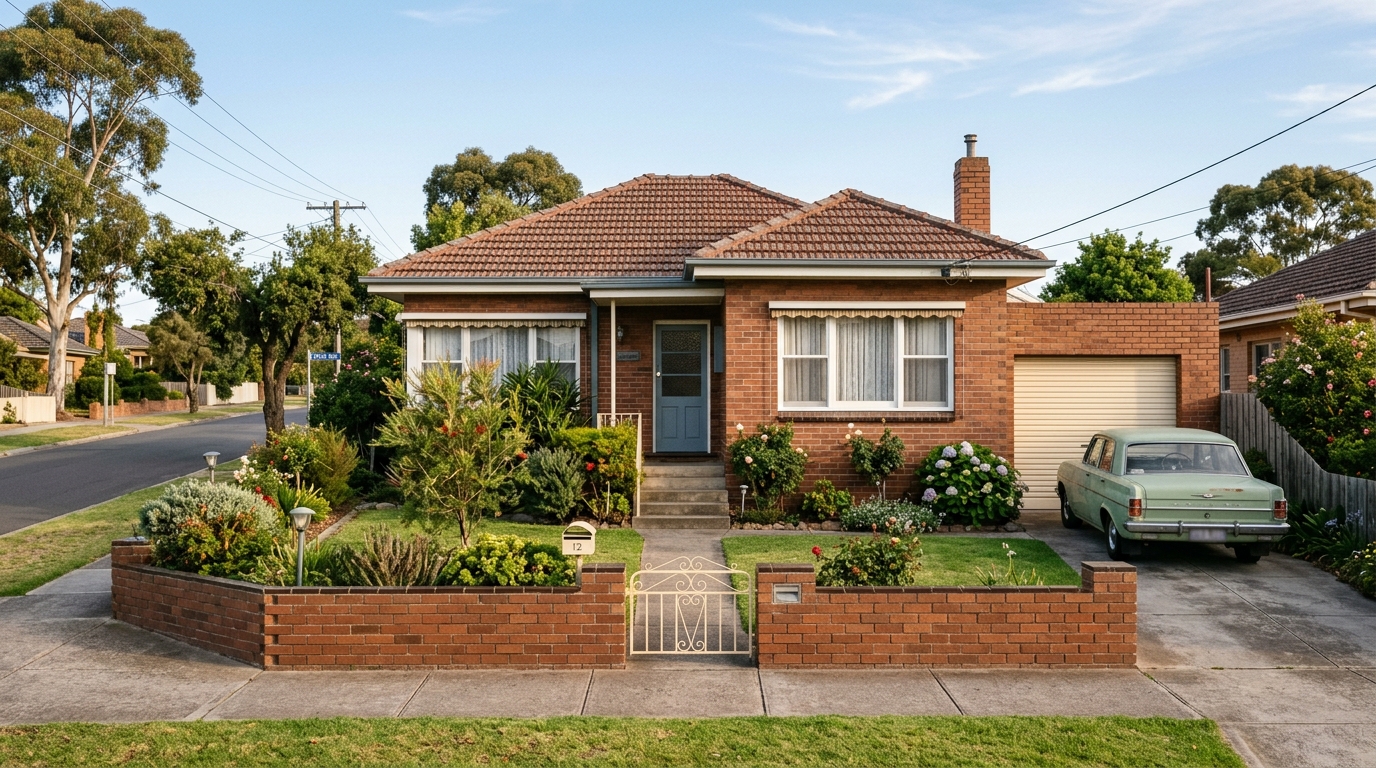
Buy an established home as an investment now, and from 1 July 2027 you can no longer deduct the loss against your income tax the way investors have for decades. The change applies to established properties that were not already held when the reform was announced at 7:30pm AEST on 12 May 2026, under the federal budget reform that is now law. Anything you held at that time keeps the old rules until you sell it — genuine grandfathering, not a temporary reprieve.
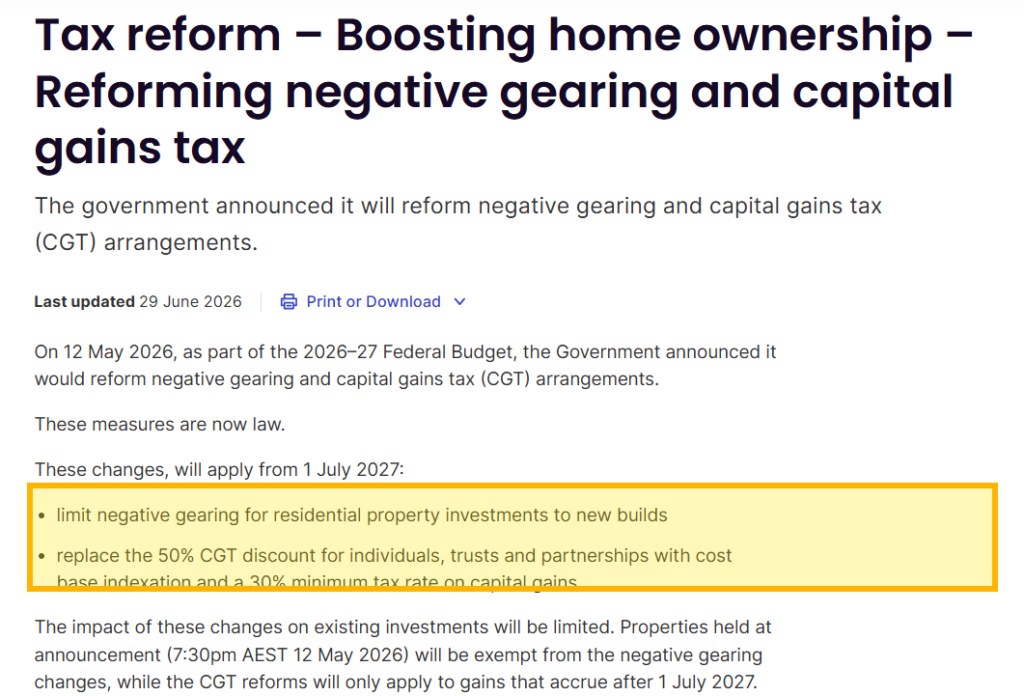
Even so, the deduction hasn’t disappeared entirely. Investors can still offset a loss against residential rental income and residential capital gains, and unused losses carry forward against future residential property income or capital gains. What’s gone is the ability to use an established-home loss to reduce tax on your salary or other income.
New Builds Still Get the Old Negative Gearing Deal
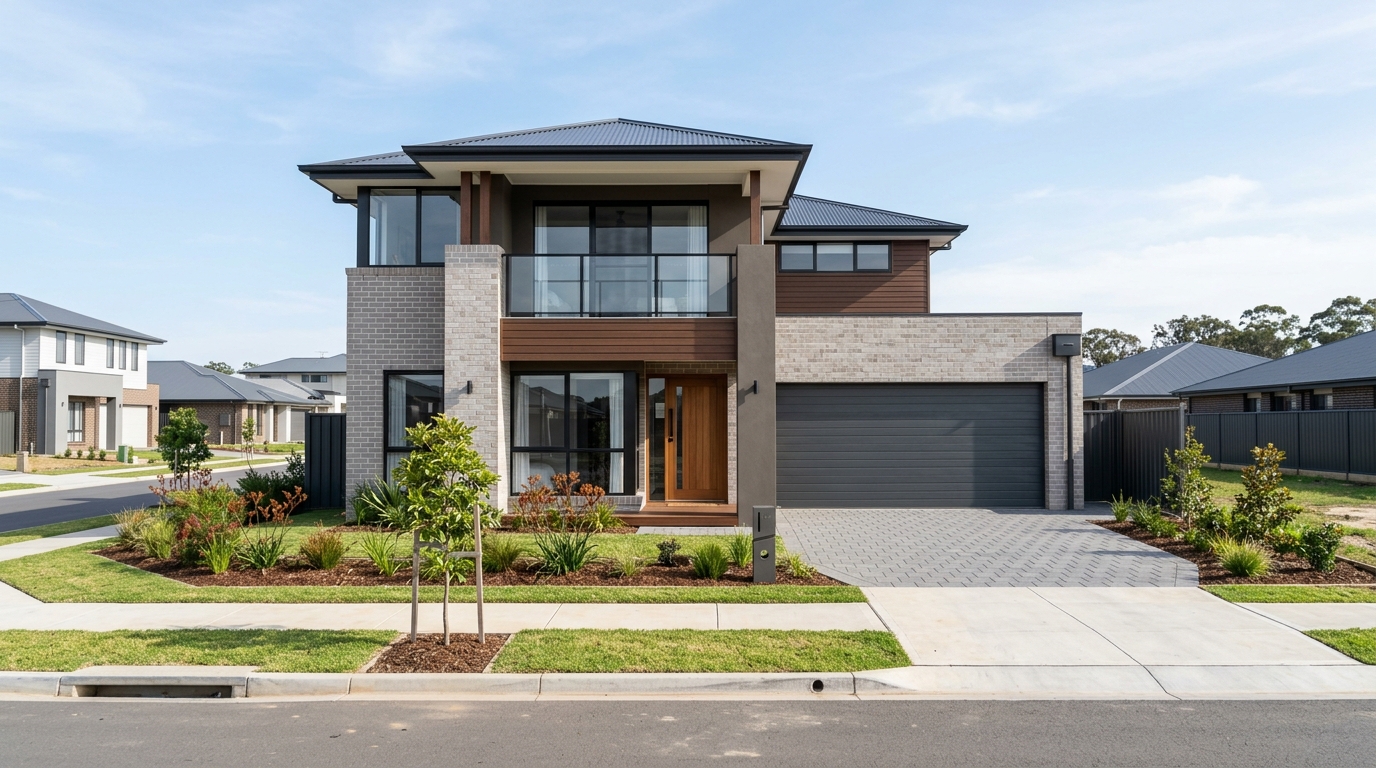
Build or buy a genuinely new dwelling, and negative gearing works exactly as it always has — full deductibility against income tax, no cutoff date. The definition matters here: a qualifying new build means construction on vacant land, or a demolition that increases the number of dwellings on the site. A straight knockdown-rebuild that replaces one house with one house doesn’t qualify, since it adds nothing to housing supply. That distinction is the whole point of the policy — Treasury wants investor money flowing into new construction, not competing with first-home buyers over the same existing stock.
Capital Gains Tax Is Changing More Slowly
So far, CGT hasn’t moved for most investors, and won’t until 1 July 2027. Until then, the 50 percent discount on gains held longer than a year still applies exactly as before. From that date, the flat 50 percent discount is replaced, for gains accruing after it, by an inflation-based adjustment, plus a 30 percent minimum tax rate that applies regardless of your income bracket.
Buy an asset before July 2027, and it keeps the 50 percent discount if you sell before then. Sell after that date, though, and the calculation splits: the old rules tax gains that accrued before July 2027, and the new rules tax gains after, using either a formal valuation at the cutover date or a time-based apportionment formula. Your own home stays exempt throughout, and pensioners and income support recipients don’t face the 30 percent minimum rate. Meanwhile, new-build investors even get a choice — stick with the old 50 percent discount or switch to the new inflation method, whichever works out better.
If You Already Own an Investment Property
Nothing changes for anything you bought before the cutoff dates. Hold an established home as an investment at the 12 May 2026 announcement, and it still lets you negative gear against income tax under the old rules until you sell it, not just during a transition window. Sell a property before 1 July 2027, and it still gets the full 50 percent CGT discount. The reform targets future purchases, not existing portfolios — so the practical question for current owners is really just what happens if you buy again, not what happens to what you already hold.
Key Dates: What Changes When
What the Negative Gearing Change Means If You’re Buying Now
The math has shifted firmly toward new construction. An established three-bedroom house in an existing suburb no longer lets you negative gear against your salary, while the equivalent new build in a growth corridor like Yarrabilba, Wyndham Vale or Alkimos still does, in full, indefinitely. That’s not a small difference for anyone running the numbers on serviceability. It also lines up with where a lot of new supply is going up in the first place — the same greenfield suburbs already carrying most of Australia’s new housing construction.
There’s a lending angle here too. A bank still counts a negatively geared loss the same way it always has when assessing serviceability — but only if that loss reduces your tax bill. Buy an established home under the new rules, and the loss no longer does that, which changes how a broker or lender might frame your borrowing capacity even before tax time arrives. In practice, that pushes the new-build-versus-established decision earlier in the process, right back to the point where you’re comparing suburbs and off-the-plan options in the first place.
For anyone buying an investment property now, new versus established is a tax decision first and a property decision second. The trap is buying a new build purely for the deduction. New stock in a growth corridor can carry a builder’s margin and slower early price growth, so the tax saving needs to be weighed against that rather than treated as free money.
The Numbers Behind the Policy
Treasury’s own modelling expects roughly 75,000 properties to shift from investors to owner-occupiers over the next decade, as the established-home market becomes less attractive to buy-to-let investors. The same modelling expects the market to deliver about 35,000 fewer new homes over that period, since reduced overall investor demand outweighs the redirection toward new construction. In total, the policy raises an estimated $77.2 billion in revenue over ten years, $3.6 billion of it in the near term. Full details of the reform sit on the ATO’s own explainer page. It also broke a specific election promise — the government had ruled out exactly this kind of change before the budget, and the backflip remains politically contested even as the policy takes effect.
Related guide: Land Tax by State: Thresholds, Rates and a $700k Test
General information only, not tax or financial advice. Based on federal budget and ATO information available at the time of writing. Tax outcomes depend on your circumstances, so confirm with a registered tax agent or accountant before acting.
Correction, 30 October 2026: An earlier version said the negative gearing changes applied from 12 May 2026 and that the 30 percent minimum tax started on 1 July 2028. The ATO states the changes apply from 1 July 2027, with properties held at the 12 May 2026 announcement exempt until sold. The article has been corrected.