Help to Buy isn’t the same program as the 5% Deposit Scheme, even though people mix the two up constantly. The 5% Deposit Scheme guarantees your loan so you skip Lenders Mortgage Insurance — you still own 100% of the home from day one. Help to Buy works differently: the government actually buys a slice of your home alongside you, up to 40% for a new build or 30% for an existing one, and you only need a 2% deposit to get started. It’s smaller, income-capped, and offered through far fewer lenders — but for the right buyer it closes a bigger gap than the 5% scheme ever could. Here’s exactly how it works, what it costs you later, and who it’s actually for.
| What You’re Asking | Where It Stands Now |
|---|---|
| Minimum deposit | 2%, with no Lenders Mortgage Insurance |
| Government equity contribution | Up to 40% (new build) or 30% (existing home) |
| Income cap (FY26) | $103,000 single — $165,000 joint or single parent |
| Annual places | 10,000 for the 2026–27 financial year |
How Help to Buy Actually Works
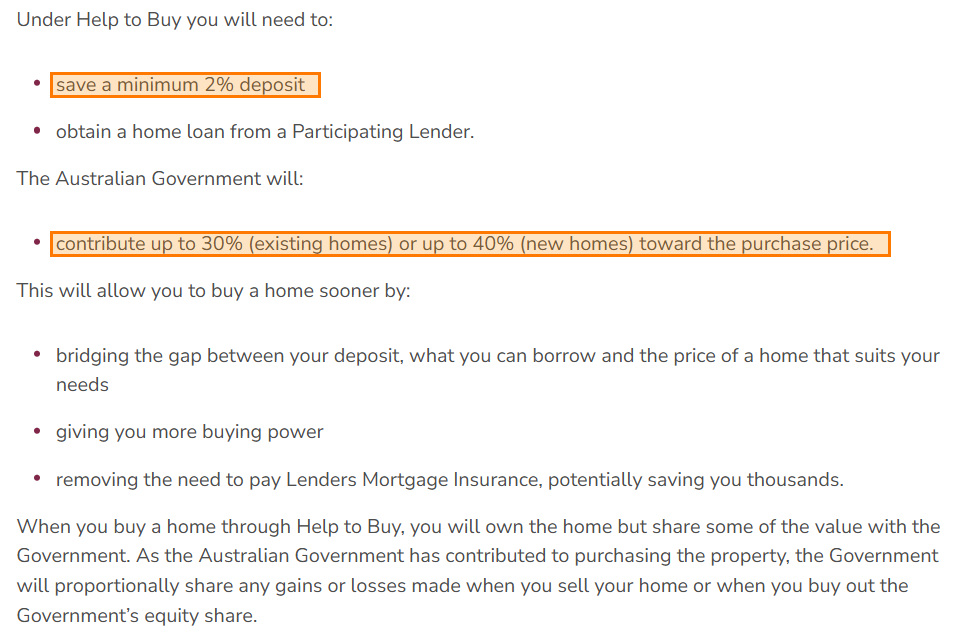
The mechanics are different from every other first home buyer scheme currently running. You save a 2% deposit and get a home loan from one of the two Participating Lenders — Commonwealth Bank or Bank Australia, for now. The government then contributes the rest of the gap: up to 40% of the purchase price for a newly built home, or up to 30% for an existing one, secured through a second mortgage that Housing Australia registers on the property.
Housing Australia’s own published example shows how this plays out. A buyer named Rob bought an $800,000 existing home with a $16,000 deposit (2%), a $544,000 loan from his lender, and a $240,000 contribution from the government. That gave him a 68% loan-to-value ratio to service on his own loan, instead of the roughly 98% he’d otherwise be carrying — and no Lenders Mortgage Insurance on top of it.
You don’t pay rent or interest on the government’s share while you hold it. What you do carry is exposure to its value: when you sell the home, or buy back the equity, the payment is calculated against whatever the property is worth at that time — not what it cost when the government bought in.
What You Can Actually Buy Under the Price Caps
Help to Buy uses property price caps too, and they’re set state by state, capital city versus rest-of-state, the same way the 5% Deposit Scheme’s are.
| State/Territory | Capital City / Regional Centre | Rest of State |
|---|---|---|
| New South Wales | $1,300,000 | $800,000 |
| Victoria | $950,000 | $650,000 |
| Queensland | $1,000,000 | $700,000 |
| Western Australia | $850,000 | $600,000 |
| South Australia | $900,000 | $500,000 |
| Tasmania | $700,000 | $550,000 |
| Australian Capital Territory | $1,000,000 | n/a |
| Northern Territory | $600,000 | $600,000 |
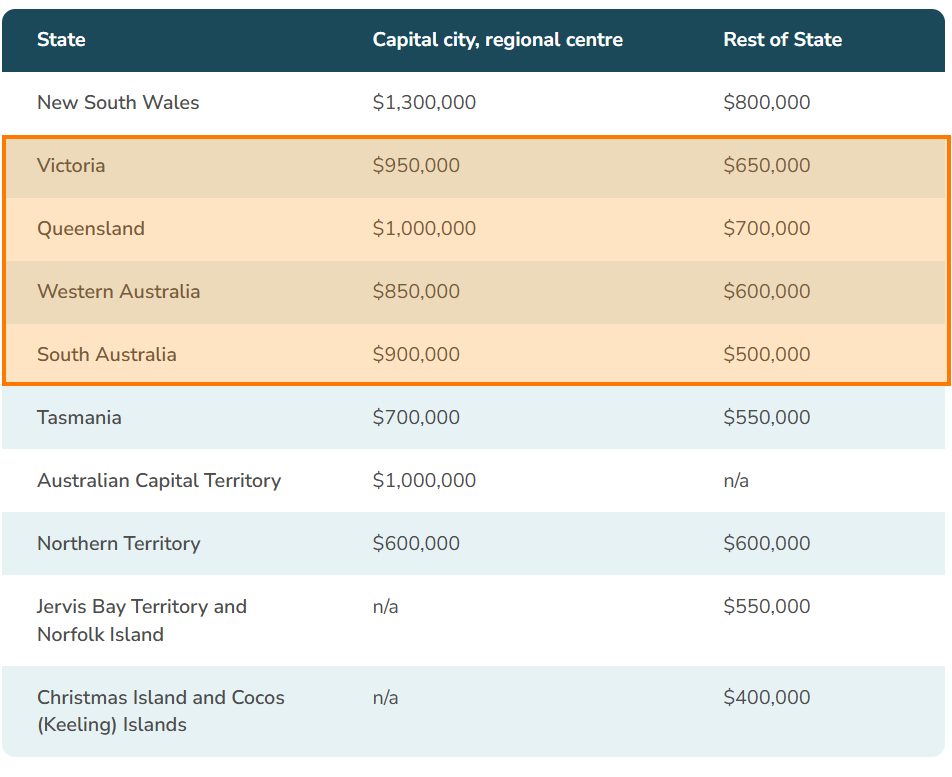
Source: Housing Australia, Help to Buy property price caps.
If you’ve read our guide to the 5% Deposit Scheme price caps, these numbers will look familiar — Housing Australia applies the same national table to both schemes, region by region. Yarrabilba, Queensland sits at a $1,000,000 cap, while Wyndham Vale, Victoria comes in at $950,000. Alkimos, Western Australia is capped at $850,000, and Angle Vale, South Australia at $900,000. That overlap matters — it means a buyer priced out of a capital city under one scheme is priced out under the other too, and a buyer who fits a growth corridor’s cap can weigh both schemes against the same property.
Help to Buy vs the 5% Deposit Scheme: What’s Actually Different
The two schemes solve the same problem — not enough deposit — in opposite ways. One guarantees your loan so you can borrow with less saved. The other has the government buy part of the home with you, so you need to borrow less in the first place.
| Help to Buy | 5% Deposit Scheme | |
|---|---|---|
| Minimum deposit | 2% | 5% |
| How it helps | Government co-owns up to 40% (new) / 30% (existing) of the home | Government guarantees the loan — no Lenders Mortgage Insurance |
| Who owns the home | You and the government, proportionally | You, 100%, from settlement |
| Income cap (FY26) | $103,000 single / $165,000 joint or single parent | None — removed October 2025 |
| Annual places | 10,000 for 2026–27 | Unlimited |
| Participating lenders | 2 (Commonwealth Bank, Bank Australia) | 30+ |
In practice, the income cap and the two-lender panel are what rule Help to Buy out for a lot of buyers before they even get to the price caps. If your income sits under the threshold and you’re comfortable with one of the two participating banks, though, Help to Buy does more to lower your actual monthly repayment — you’re borrowing against 60–70% of the purchase price instead of the full amount.
Who’s Actually Using It
Help to Buy opened to applicants on 5 December 2025 and reached full national coverage in June 2026 when Tasmania joined. Since launch, the Scheme has received more than 7,200 applications, with around 4,800 of those buyers already settled into a home and the rest still looking. Demand has been strongest in Victoria, followed by New South Wales and Queensland.
Almost 7 in 10 applications are from single applicants, including 12% who are single parents — a group the Scheme was specifically designed to reach. The median deposit used is just $30,000, and 86% of participants are buying their first home. Housing Australia has also flagged Help to Buy’s growing role for older single women, one of the fastest-growing groups facing housing insecurity: 42% of the women supported so far are aged 40 or above.
Here’s how those numbers break down.
The Catch: You’re Sharing the Growth, Not Just the Risk
The government’s share isn’t a fixed dollar figure — it’s a fixed percentage of whatever the home is worth when you pay it back. That cuts both ways, but in a market where prices tend to rise over time, it usually works against the buyer.
Take Rob’s $800,000 home from Housing Australia’s own example, with the government holding a 30% share worth $240,000 at settlement. If that property grows at a modest 5% a year — in line with long-run Australian averages — it’s worth roughly $1,303,000 after 10 years. The government’s 30% share has grown right along with it, to about $391,000. Buying that share back at the 10-year mark costs around $151,000 more than the government originally put in — not because of interest or fees, but because Rob doesn’t own that 30% of the capital growth either.
That’s the trade-off in one sentence: a smaller deposit and lower monthly repayments today, in exchange for giving up a proportional share of everything the property gains from here. The 5% Deposit Scheme doesn’t have this cost at all, because you own 100% of the home — and 100% of its growth — from day one.
Which Scheme Actually Fits You
If you can scrape together a 5% deposit and just need to avoid Lenders Mortgage Insurance, the 5% Deposit Scheme is the simpler option — no income cap, unlimited places, and more than 30 lenders to shop between.
Help to Buy is worth the extra paperwork if you’re genuinely short of even a 5% deposit, or if your borrowing capacity is tight and a smaller loan changes what you can actually afford to service — particularly relevant while the cash rate outlook stays uncertain. It only works, though, if your income sits under the cap and you’re comfortable applying through Commonwealth Bank or Bank Australia.
FAQ: The Help to Buy Scheme
Is Help to Buy the same as the 5% Deposit Scheme?
No. The 5% Deposit Scheme guarantees your loan so you avoid Lenders Mortgage Insurance while owning 100% of the home. Help to Buy has the government co-own up to 40% (new) or 30% (existing) of the property with you, in exchange for a smaller 2% deposit.
How much deposit do I actually need for Help to Buy?
A minimum of 2% of the purchase price. You also need to be at least 18, an Australian citizen, and not own other property in Australia or overseas, with limited exceptions for single parents buying out a former partner’s share.
What happens when I sell or want to buy back the government’s share?
You can make voluntary incremental payments, buy back the government’s equity in a lump sum when you’re able to, or sell the property. Whichever way you do it, the amount is always calculated against the property’s value at the time of payment — not the price you originally paid.
Can I use Help to Buy for an apartment or vacant land?
Yes. Help to Buy covers houses, townhouses, apartments, units and duplexes, new or existing, as well as vacant land for a new build, provided you’ve signed a building contract with an eligible builder and the total stays under your location’s price cap.
This article is general information about the Australian Government Help to Buy Scheme, based on Housing Australia’s published guidance as at September 2026. It isn’t financial or legal advice. Eligibility rules, income thresholds and price caps can change — check firsthomebuyers.gov.au or speak with a Participating Lender before making a decision.